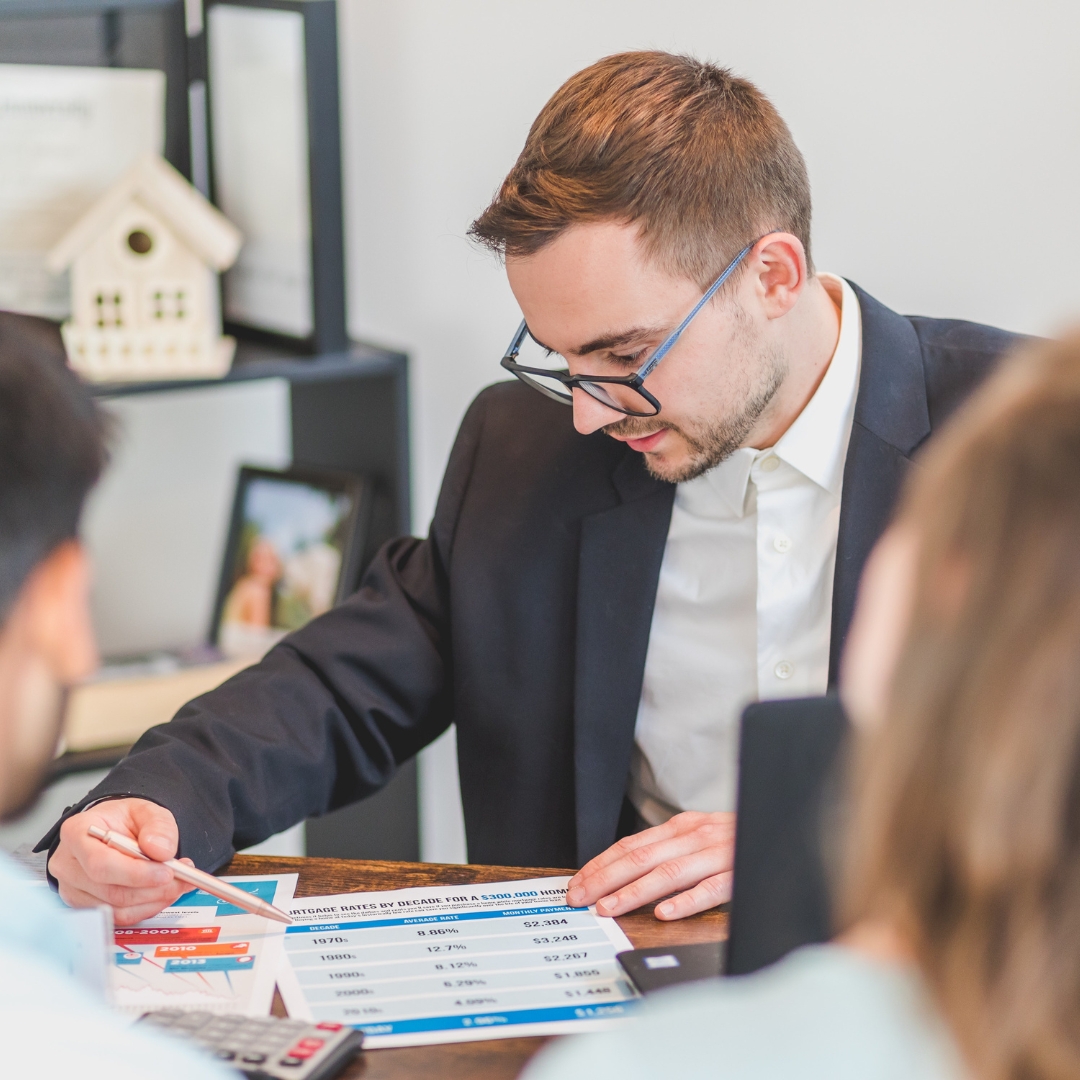
Here are some tips for efficiently evaluating mortgage proposals:
1. Compare interest rates
A small difference in interest rates can translate into significant savings over time. Make sure to compare the Nominal Annual Rate (TAN) and the Annual Percentage Rate (APR or TAEG), as they reflect the total cost of the loan.
2. Consider the Total Amount Imposed on the Consumer (MTIC)
The MTIC is the total amount that the consumer will have to pay to the bank, including the borrowed amount, interest, taxes, insurance, and fees. The lower the MTIC, the more advantageous the loan.
3. Analyse the insurance
Insurances such as life insurance and home multi-risk insurance are mandatory components of mortgages. Compare the conditions and prices offered by different institutions.
4. Check the commissions and associated costs
Some banks may offer attractive interest rates but compensate with high commissions. Evaluate opening, maintenance, early repayment commissions, and other additional costs.
5. Consider flexibility
Some banks may offer more flexible conditions, such as grace periods or the possibility of early repayment without penalties. Pay attention to these “details” and include them in your consideration when making a decision.
Comparing mortgage proposals may seem complex, but considering these factors will help you make an informed choice and find the most advantageous option for your profile and financial needs.
Conduct a careful analysis and consider seeking financial advice to ensure you make the right decision.